TradingKey - Shares of Intel (NASDAQ: INTC) traded up 12.14% to finish at $121.78 on Monday following a breakout above resistance at $116.16. One of the catalysts for the recent rally in the tech sector has been the announcement by Meta Platforms (NASDAQ: META) around the development of its own personal AI agent, Muse. It is widely believed that as AI assistants and other similar technologies become more sophisticated and mainstream, there will be a stronger reliance on CPUs to support the work of AI assistants in conjunction with GPUs. As such, the long-term growth potential of Intel’s CPU business looks good.
Agentic AI Is Strengthening the CPU Demand Case
Given the workloads for agentic AI, CPU demand is significantly greater than previously thought. Agentic AI workloads require significant CPU resources for tasks such as orchestration, networking, and other workloads.
Intel is currently facing supply constraints, with market demand exceeding available product supply. The company’s AI and Data Center divisions accounted for $6.3 Billion of the company’s $15.1 billion in Intel Products revenue, while total company revenue was $16.1 billion for the quarter ending in June.
I think the biggest development for Intel is the fact that they are no longer solely dependent on the PC market for growth. The data center market is beginning to look very appealing for Intel again.
Q2 Shows a Much Stronger Operating Business
For the quarter, Intel reported revenue of $16.1 billion which was an impressive 25% increase from the year prior.
Impressive operating margin expansion and gross margin expansion aided the bottom line. For the quarter Intel reported a 41.8% non-GAAP gross margin, 17.2% non-GAAP operating margin, and $0.42 of non-GAAP EPS.
The $11.0 billion GAAP loss for the quarter was surprising to most, but should not be perceived negatively. The loss was largely attributed to a mark to market adjustment for escrowed Intel shares held for the benefit of the U.S. government, which totaled approximately $12.5 billion.
Intel expects continued positive momentum for the business. For the current quarter, Intel expects revenue between $15.8 and $16.8 billion. Non-GAAP gross margin is expected to be 42% and non-GAAP EPS is expected to be $0.38.
Panther Lake Gives 18A a Fresh Validation Test
With the launch of Google’s Googlebook, platforms have increased for both companies. For now, the models in the Googlebook program are powered by Intel and Qualcomm processors. Intel, however, has confirmed that processors for Acer, ASUS, and Lenovo will be powered by Panther Lake processors under the codename, “Core Ultra Series 3”.
It is important to understand that Panther Lake is Intel’s first mainstream client platform built on the Intel 18A process. Therefore, customer adoption for Panther Lake processors will demonstrate how Intel’s 18A process will perform at a larger scale.
Intel 18A is described as an improvement over the Intel 3 architecture by 18% in performance at the same power requirements, and 38% in power savings at the same performance level. Additionally, Intel 18A will provide a 30% increase in chip density.
18A Progress Is Real, but Foundry Still Loses Billions
Intel Foundry is using ASML High-NA EUV technology on select layers of a subset of Panther Lake processors, with more than one million wafers processed across certification, R&D and production.
That is certainly good news, but Intel Foundry Services remains the largest risk in the restructuring. Foundry revenues were $5.8 billion in the second quarter, up 31%, but the segment lost $2.1 billion. Revenues from external customers were only $293 million, meaning the rest of the revenues came from internal Intel production.
What would change my view is if the company disclosed external customer revenues and loses continued to decrease.
SK Hynix Talks Add U.S. Manufacturing Optionality
Reuters reported SK Hynix is considering partnering with or leasing from Intel’s Ohio Fab to produce memory chips. According to the report, Intel and large cloud customers may also participate in the joint venture.
Although no final decisions have been made, this partnership could benefit Intel and help alleviate the memory shortage.
Valuation Now Requires Better Execution
While Intel's recent revitalization is undeniable, its stock has already reflected this and then some. With its recent upticks, Intel is up over 200% from the beginning of the year, and while bullish sentiment remains, Intel is currently trading at $121.78.
At this point, Intel has not publicly disclosed when it will release its next set of earnings. With that said, I would seek out information regarding progress made with DCAI, gross margin expansion, Panther Lake volumes, 18A, and potential external customer wins with Intel's Foundry business.
Intel Technical Analysis: INTC Breaks $116.16 as Bulls Target $126.78
Intel's stock currently trades at chart price, and the bullish target is $126.78. Intel broke resistance in the $111 to $116.16 range, and experienced a strong 4-hour trend.
I consider Intel’s break and close above $116.16 to be a bullish sign. After several months of forming lower highs beneath a descending trendline, Intel may have reversed its long-term downtrend.
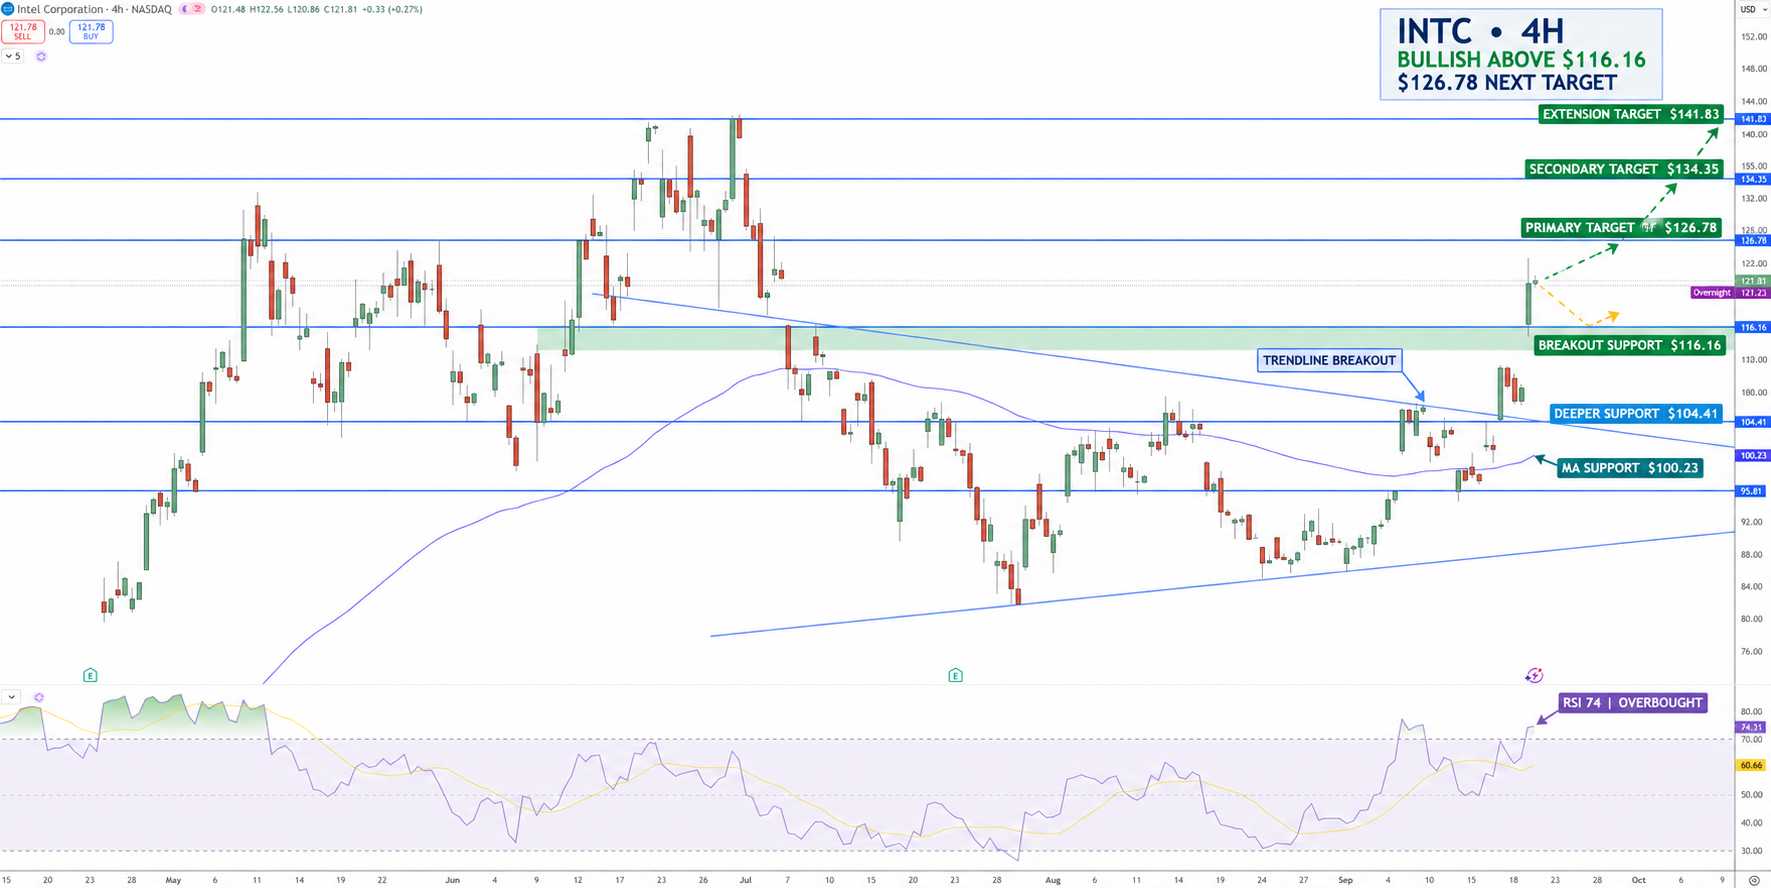
Intel Stock Price Chart - Source: Tradingview
RSI is at about 74. This is well above the signal line at about 61. The higher the RSI reading, the more it indicates that the market is overbought. The short-term trend of the market is up, and higher prices should continue. However, the market can take a rest and consolidate after a big move up. Therefore, prices can pull back to the 116.16 support level before continuing higher.
If the price moves higher, the first target would be 126.78. A move above 126.78 would increase the likelihood of higher prices, with the next targets at 134.35 and 141.83.
If prices fall, they are likely to find support at 116.16. If prices fall below 116.16, the 104.41 support level would be the next likely level that prices would test. The 100.23 level would also provide support and be a floor to the down move.
My basic bullish bias would remain as long as prices stay above 116.16. The bullish bias would be better supported if prices pull back to 116.16.
Key Levels
• Key Support Levels: $116.16, $104.41, $100.23
• Key Resistance Levels: $126.78, $134.35, $141.83
• RSI: 74, overbought
Why is Intel stock in focus now?
Agentic AI is driving CPU demand, and Intel is in the process of restructuring. Second quarter revenue increased by 25%. The company's Data Center and AI (DCAI) revenue increased by 59%. Intel is improving its gross margins, and its processor, Panther Lake, is gaining Steam in Googlebook laptops.
What level confirms a stronger INTC breakout?
If the bulls can close the 4 hour candle above $126.78, it confirms the breakout, and the next target becomes $134.35. If $116.16 is breached, it would be a bearish turnaround and bring $104.41 into focus.
Bottom Line
Intel reported improved gross margins and cash flows and continued strength in the company’s data center business. The company is also improving its processor architecture. The biggest concern for Intel is its Foundry business, which lost $2.1 billion during the quarter. Positively, the stock is currently trending higher and is above the 116.16 level. From here, a move above the 126.78 level should open the way for further gains to the 134.35 level. A move below 116.16 would negate the recent improvement.
Find out more