TradingKey - Shares of Advanced Micro Devices (NASDAQ: AMD) hit a new all-time high on Monday, finishing at $615.52, and giving the chipmaker a market capitalization of over $1 trillion. While the stock has been strong throughout the year, as it has become increasingly apparent that AMD can be a significant CPU provider beyond Intel, Monday’s rally showed investor belief that AMD can be a strong provider of AI compute beyond Nvidia. As the data center grows, so will AMD’s income statement. However, if the company wants to be valued around $1 trillion, it will need strong operating and financial numbers beyond 2026.
Data Center Revenue More Than Doubled
Q2 revenues for AMD came in at $11.54 billion, representing a 50% increase from the year prior. Data Center revenues more than doubled to $6.72 billion, and represented 58% of total revenues for the quarter.
Strong demand for AMD’s EPYC processors and Instinct GPUs, together with the absence of the prior-year MI308 export-control inventory charges, helped lift Data Center operating income to $2.1 billion from a $155 million operating loss in the prior-year quarter. Client Computing revenues increased by 23% to $3.06 billion. A 31% decrease in Gaming revenues to $779 million was mainly attributed to lower semi-custom revenue.
The big shift for AMD has been the increase in data center revenues and profits, which increases their exposure to AI infrastructure.
Q3 Guidance Points to Another Record Quarter
In accordance with AMD’s Q3 guidance, we expect another record-breaking quarter. They expect approximately $13 billion in revenues, which is a ~41% increase from last year and a ~13% increase from last quarter. They expect non-GAAP gross margins to be ~56% this quarter.
During their earnings call they noted the second half of the year is off to a great start with accelerating EPYC demand, expanding Instinct deployments and Helios beginning to ramp.
The real question is not if there is AI workloads, that is clearly acknowledged. The question is if AMD is able to meet demand and continue to grow at these rates. Most expect this level of growth to continue through 2027.
Helios Is Central to AMD's Nvidia Challenge
Helios shifts AMD’s competitive positioning from selling components to AI systems at rack-level. Helios makes use of Instinct accelerators and EPYC CPUs, and interconnects and high bandwidth memory. Helios is also accompanied by ROCm software.
According to AMD,Helios is being used by various AI and Cloud companies and services including Anthropic, Meta, and Microsoft, as well as OpenAI and Oracle.
While Nvidia dominates the GPU market, it also has deep-rooted competitive positions in other adjacent markets such as System Architecture and Networking. Helios allows AMD to compete for AI systems at the rack level, as opposed to competing for individual AI accelerators.
Meta and Anthropic Add Large Deployment Visibility
Meta Platforms and AMD announced a multi-year supply agreement, where Meta will purchase up to 6 Gigawatts of AMD’s Instinct GPUs. Shipments supporting the first 1 Gigawatt deployment are expected to begin during the second half of 2026, using a custom MI450-based GPU platform built on the AMD Helios rack-scale architecture. The system will be powered by AMD’s 6th Gen EPYC CPUs and ROCm.
Anthropic, a rival AI company to OpenAI, will also use AMD’s Instinct AI Systems. In September 2023, Anthropic announced it would partner with AWS (a subsidiary of Amazon) to build and deploy large language models.
Anthropic has announced plans to deploy up to 2 gigawatts of MI450 GPUs, beginning in 2027. Deployment of the first gigawatt is expected to begin in the first half of 2027.
These contracts provide more visibility than the average contract, but revenue from them is not certain.
Agentic AI Could Help EPYC as Well as Instinct
Chipmakers stand to benefit from the recent interest in agentic AI. Industry analysts have predicted that the workloads generated and accelerated by GPUs in AI applications will increase data center workloads dramatically and quickly.
AMD can capitalize on this trend through both its EPYC processors and Instinct accelerators. Because EPYC processors control and orchestrate AI workloads, and Instinct accelerators perform the workloads, AMD can be a more integrated supplier compared to NVIDIA.
ROCm Remains the Critical Competitive Test
AMD’s biggest problem compared to Nvidia is software. AMD has been aggressively investing in ROCm, but it will take time to close the software gap against Nvidia and its CUDA framework.
Anthropic is a positive development for AMD. As part of the partnership, Anthropic and AMD will use Claude to optimize workloads for AMD Instinct GPUs and accelerate ROCm development.
Although AMD offers competitive hardware, if ROCm software continues to be harder to integrate compared to CUDA, AMd may not gain as much market share as expected.
Valuation Is Now the Biggest Risk
AMD crossed the $1 trillion market cap on September 21, 2026 for the first time. According to Reuters, AMD’s stock price had increased by 185% by that time this year.
The markets expect strong growth and major orders from Hyperscale customers for AMD’s hardware and services in the coming years.
AMD has not yet officially announced its next earnings date. I will be looking for changes in gross margins, Q3 2026 revenues, Helios shipments, Data center revenues, ROCm customer deployments, and management's Outlook for the AI and cloud segment for 2027.
AMD Technical Analysis: Breakout Above $584.90 Puts $617.80 in Focus
AMD’s latest completed close was $615.52, close to the chart price of $615.43. The 1-hour chart remains strongly bullish after breaking out above $584.90. Price is keeping the rising channel by not giving back the move and instead trading at one of the highest levels.
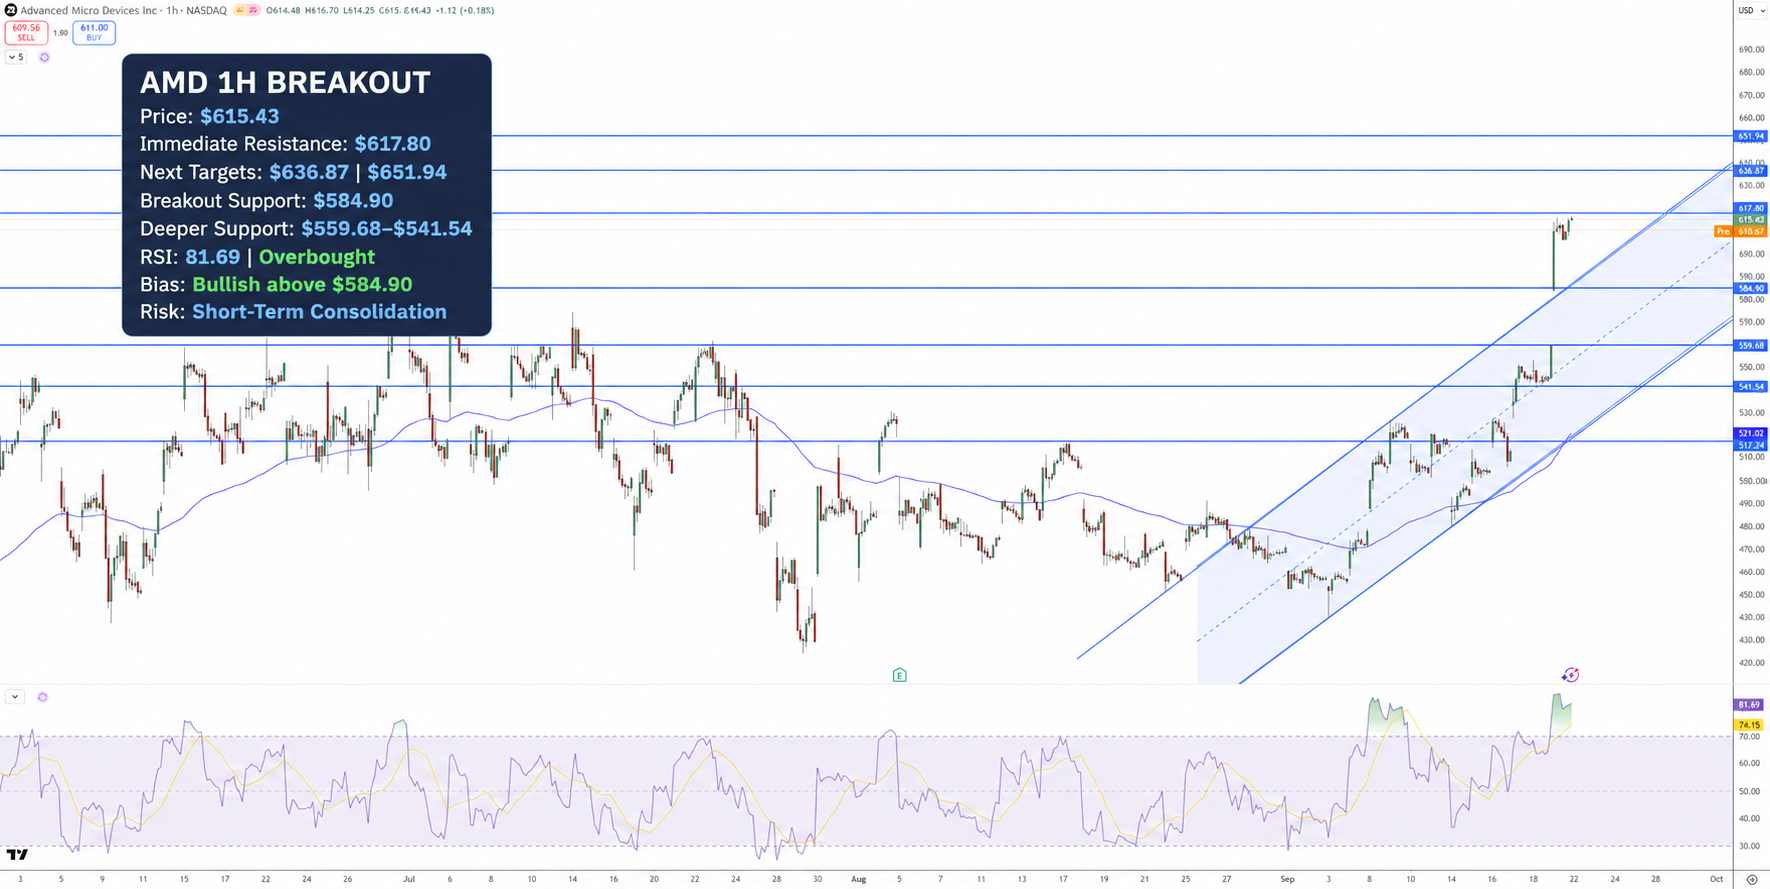
AMD Price Chart - Source: Tradingview
The rising channel means the price of AMD has continued to increase. Because of this, the rising channel has a upward slope. The channel’s upper bound is $617.80. Further increase beyond this would lead to $636.87 and $651.94 respectively.
RSI is at 82. Because it is above the signal line of 74, this indicates that buying is strong. However, a spike this high increases the probability of a short-term pullback or consolidation. The channel’s lower bound is $584.90. A further decrease from here would lead to $584.90 and then the $559.68 to $541.54 support area. I believe the overall trend will remain bullish as long as the price remains above $584.90.
Current bullish trend and RSI at 82 increases the probability of short-term consolidation or profit-taking.
Key Levels
• Recent close: $615.52
• Support: $584.90, $559.68 to $541.54
• Resistance: $617.80, $636.87 and $651.94
• RSI: 82
• Target: $636.87 and beyond if $617.80 is taken out.
Why is AMD stock in focus now?
AMD has announced a more than two-fold increase in Data Center revenue, and the company has recently signed long-term agreements with Huge AI Customers. Helios, AMD’s next-generation rack-scale AI platform, is also ramping up. Because of this, and their other recent announcements, AMD crossed the $1 Trillion market cap on September 21st.
What level confirms a stronger AMD breakout?
An even better sign would be an hourly closing price above $617.80. This would tell us that the resistance above $617.80 has been cleared, and the next target would be $636.87 and then $651.94. On the downside, a break below $584.90 would negate the breakout signaled at $584.90.
Bottom Line
AMD’s recent earnings and announcements further demonstrate that the company is quickly gaining market share in the Data Center, helping them gain large AI customers. In addition, AMD’s Agentic AI announcements should further increase the companies GPU and CPU Sales.
The key to trading AMD is managing expectations. Because AMD is now a $1 Trillion dollar company, they will need to continue their rapid growth and upside surprises, especially in the AI sector. Overall, AMD should be biased higher between $584.90 and $617.80, with upside potential to $636.87. A move below $584.90 changes the bias negatively.
Find out more